Comprehensive Guide to Solar Liability Insurance for Homeowners with Solar Panels
Understanding Solar Liability Insurance and Its Importance for Homeowners
Solar liability insurance is a specialized form of insurance coverage provided by homeowners insurance policies or standalone products to address the unique liability risks created by solar panels and solar power systems installed on residential properties. Unlike standard homeowners insurance, which primarily offers coverage for traditional property damage and personal liability, solar liability policies explicitly cover risks arising from solar panel operation and installation.
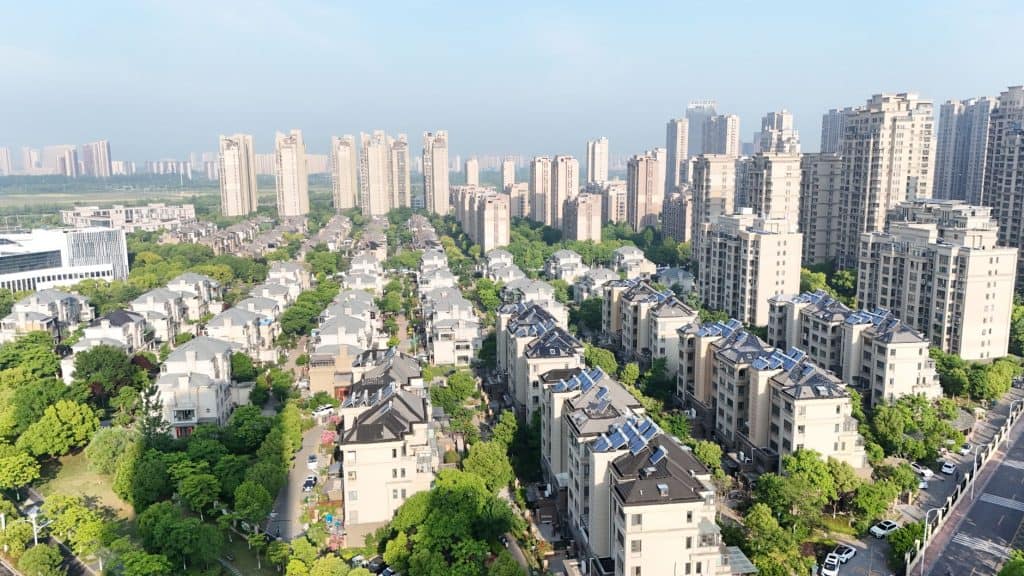
The presence of solar panels increases homeowner liability exposure through potential electrical malfunctions, panel detachment, or defects in installation by solar installers. These can cause injury to third parties or damage to neighboring property, a risk often not comprehensively covered under standard policies.
Standard homeowners insurance policies often exclude or impose coverage limits on claims related to electrical equipment, including solar panels, per underwriting guidelines or policy endorsements. For instance, many policies exclude fire damage caused by electrical failures unless specific riders are purchased. This leads to significant coverage gaps for solar-specific risks, making solar liability insurance necessary to cover injury or property damage claims directly linked to the solar system.
Homeowners should verify whether their home insurance cover solar panels explicitly by reviewing their policy language or requesting documentation from insurance companies to avoid uncovered liability exposures.
Types of Solar Liability Coverage Available and What They Protect
Insurance companies offer solar liability insurance through different products designed to cover risks associated with solar power systems, allowing homeowners to select coverage suited to their specific solar installation.
- Standard Homeowners Liability Extensions: Some homeowners insurance policies include automatic extensions covering bodily injury and third-party property damage caused by solar panels, with typical coverage limits ranging from $250,000 to $500,000. These extensions usually exclude coverage for physical damage to the solar system itself.
- Standalone Solar Panel Insurance or Add-on Riders: These policies explicitly insure against solar panel damage, electrical faults, installation errors, and associated liability claims. They often comply with technical standards such as the National Electrical Code (NEC) Article 690 in the US or equivalent European technical installation directives. Coverage limits are customizable but commonly start around $500,000 and can be increased depending on system size and homeowner preference.
- Umbrella Policies: Umbrella policies provide coverage beyond standard and solar-specific policies, typically starting at $1 million in liability limits. These policies protect homeowners against large solar panel claims related to third-party injury or property damage that exceed underlying policy limits.
Coverage components commonly included in solar liability policies are:
- Physical damage protection for solar panels, frames, and inverters
- Liability coverage for personal injury resulting from installation, maintenance, or malfunction
- Protection against electrical fire hazards associated with tier 2 solar systems, which incorporate higher voltage electronics and complex inverter technology
- Coverage for third-party property damage caused by detachment or failure of solar components
Tier 2 solar systems—defined by industry standards as those with integrated advanced electronic controls, energy storage, or complex inverter arrays—receive increased insurance scrutiny due to documented elevated fire risk and electrical malfunction rates, leading to higher premiums and stricter coverage conditions.
How Adding Solar Panels Affects Homeowners Insurance Premiums and Coverage Terms
Adding solar panels to a residential property requires notifying insurance companies to update homeowner risk profiles and coverage terms, which typically results in an insurance premium increase reflecting the higher replacement value and liability exposure.
Market data from jurisdictions with established residential solar markets (e.g., Florida, California, and parts of Central Europe) indicate insurance premium increases between 5% and 20% after adding solar panels, with premiums adjusted based on solar system capacity (measured in kW), panel type (tier 1 versus tier 2), installation quality, and geographic exposure to hazards such as hurricanes or wildfires.
Insurance companies require documentation verifying that solar panels were installed by certified solar installers with recognized credentials (e.g., NABCEP certification in the US or EU installer certifications compliant with IEC 62446). Certified installations reduce insurer risk assessments, mitigate premium surges, and facilitate claims processing. Conversely, uncertified or self-installed systems may lead to higher premiums or refusal to cover solar-related claims.
Failure by homeowners to inform insurers about solar system additions can result in policy cancellation, denial of claims related to solar equipment, or post-loss coverage disputes, emphasizing the need to update home insurance cover solar panels explicitly after installation. The notification process usually requires submitting installation certificates, compliance with local building codes (such as NEC 2017/2020 in the US or EU solar system regulations), and proof of adherence to safety standards.
Common Liability Risks Associated with Residential Solar Panel Systems
Residential solar systems present specific liability risks that underpin the rationale for dedicated solar panel insurance:
- Third-party Injury: Physically detached panels or mounting hardware during storms or aging deterioration can injure visitors or neighbors. For example, wind speeds exceeding manufacturer design thresholds (commonly 140 mph or 225 km/h) have caused such failures documented in insurance claims.
- Installation Faults: Faulty electrical connections or structural mounting errors by uncertified solar installers can cause electrical shocks, fires, or structural damage. Post-installation inspections per UL 1703 or IEC 61730 standards reduce these risks.
- Fire Hazards: Tier 2 solar systems, integrating energy storage and advanced inverters, exhibit an elevated risk of electrical fires from short circuits or inverter malfunction, substantiated by increased claim frequency in industry reports.
- Net Metering Arrangements: Systems feeding excess power back to the grid may raise liability concerns over grid disturbances, property damage, or safety incidents downstream of the solar installation. Liability and operational risks require insurers and homeowners to evaluate system interconnection agreements and local utility regulations to determine coverage adequacy.
Claims data from markets with dense residential solar deployment show that electrical faults and installation errors represent over 60% of solar panel claims, highlighting the need for specialized insurance policies that cover these distinct liabilities.
Steps for Homeowners to Secure Adequate Solar Liability Insurance Coverage
To effectively insure your solar panel installations and limit liability exposure, homeowners should execute the following steps:
- Review Current Homeowners Insurance Policies: Identify whether existing homeowners insurance explicitly covers solar panels or if limitations/exclusions exist regarding liability or property damage linked to solar systems.
- Engage Insurance Companies or Brokers: Source quotes for solar panel insurance products or add-on riders that provide defined coverage for installation faults, fire risk, and third-party liability resulting from solar operations.
- Prepare Targeted Coverage Inquiry Checklist: Include questions covering coverage limits (starting at minimum $300,000 to $1 million depending on risk), inclusion of tier 2 solar systems, claims handling for solar panel claims, and additional endorsements needed for net metering.
- Verify Installer Certifications and Manufacturer Warranties: Compile official documentation demonstrating installation by certified solar installers compliant with local standards and manufacturer certifications (e.g., IEC, UL listings).
- Update Policies After System Modifications: Promptly notify insurers of any solar system upgrades, expansions, or replacements, submitting updated installation and compliance documentation to adjust coverage and maintain continuous protection.
Following these sequential steps supports securing insurance policies optimized for solar power system risks and minimizes the potential for claim denial or insufficient coverage.
Comparison of Insurance Products for Solar Power Systems in Residential Settings
Homeowners typically select among three main insurance product categories when seeking to insure solar power systems on their property:
| Insurance Type | Scope of Coverage | Typical Coverage Limits | Cost Considerations | Claims Process |
|---|---|---|---|---|
| Standard Homeowners Insurance (with solar extensions) | General property and liability including limited solar panel coverage; usually excludes system damage | $250,000 to $500,000 liability | Minor to moderate premium increase (5-10%) after adding solar panels | Claims processed through standard homeowners systems; potential delays or denials for solar-specific incidents |
| Standalone Solar Panel Insurance or Riders | Explicit coverage for panel and inverter damage, installation faults, electrical issues, and third-party claims | Variable, typically $500,000 to $1 million, adjustable based on system complexity | Additional premium over homeowners insurance; depends on system size and tier (1 or 2) | Handled by specialized carriers with solar technical expertise; faster and more accurate claims responses |
| Umbrella Policies | Excess liability coverage over base policies including solar-related claims | Starting at $1 million, scalable according to homeowner’s risk profile | Higher fixed premium reflecting broad, high-limit coverage | Claims handled as excess liability, providing resources for large-scale solar panel claims |
Bundling solar coverage with homeowners insurance is commonly cost-effective for smaller systems but may lack adequate coverage for advanced or large-scale systems, where standalone or umbrella policies provide clearer terms and higher coverage limits reflective of higher liabilities.
Specialized insurers focusing on renewable energy offer policies designed for solar system nuances, including compliance with international standards (IEC 61701 for corrosion resistance, IEC 61730 for module safety). These insurers often provide tailored underwriting reflecting solar system technology and construction type, improving risk management and claims service quality.
With increased residential solar adoption projected for 2026-2027, market offerings for solar insurance products continue to expand, making specialized solar panel insurance a strategic consideration for homeowners.
Legal and Regulatory Factors Affecting Solar Liability Insurance in Key Markets
Insurance coverage for solar panels is shaped by legal and regulatory frameworks in jurisdictions where solar installations occur, directly impacting policy requirements and coverage scope.
For Solar Plus Garden’s operating markets such as Estonia and Serbia, regulations require that entities like Estonian OÜ and Serbian DOO ensure insurance policies cover solar panel-related liabilities comprehensively, consistent with local regulatory standards for energy producers and community investors.
Local building codes and solar installation standards define mandatory technical requirements. For example, compliance with Estonian Building Act requirements and Serbian Rulebooks on electrical installations establish benchmarks for system safety that insurers use in underwriting decisions.
Net metering frameworks in both regions impose operational and liability conditions on solar system owners, affecting insurance coverage parameters by delineating responsibility boundaries between property owners and utilities for grid interaction risks.
Comparatively, in high-hazard regions such as Florida, regulations mandate stringent hurricane-resistant design standards per the Florida Building Code, driving specialized coverage requirements for physical damage by wind. The EU places stronger emphasis on certification (e.g., CE marking, IEC compliance) influencing insurer acceptance and pricing.
Integrating Solar Liability Insurance into the Solar Plus Garden Investment and Community Model
The Solar Plus Garden project combines a 10 MW solar plant investment with a community tuin lidmaatschap, employing solar liability insurance as a core risk management instrument within its financial and governance framework.
Within the 10 MW solar plant structure, owned and operated by the Serbian DOO, solar liability insurance covers physical asset risks and injury liability to protect investor capital and ensure operational continuity. Insurers require detailed risk assessments linked to the plant’s design and installation, facilitated by certified solar installers following recognized engineering standards (such as IEC 61215 for panel performance and IEC 61730 for safety compliance).
The Garden community operates through a separate legal entity with exclusive rights to the garden concept. Membership fees fund solar operations and community activities, with associated insurance costs managed through escrow and payment control models ensuring compliance with regulatory and investor transparency standards.
This legal separation allows tailored insurance policies aligned with distinct liability profiles: one for the solar plant assets and one covering community risks, thereby mitigating cross-liability and enhancing accountability.
Structuring insurance coverage in this segmented manner supports scaling the platform while maintaining regulatory clarity, financial accountability, and risk containment within the Solar Plus Garden governance framework.
Veelgestelde vragen
- Does standard homeowners insurance automatically cover solar panels installed on my property?
- Standard homeowners insurance typically provides limited or no specific liability coverage for solar panels. Most policies require riders or standalone solar panel insurance to adequately cover risks associated with solar systems.
- How much can my insurance premium increase after adding solar panels to my home?
- Insurance premium increases generally range from 5% to 20%, subject to factors such as solar system size, tier of solar panels (tier 1 vs. tier 2), installer certification, and local environmental risks like wildfires or hurricanes.
- What liability risks does solar panel insurance cover that homeowners insurance might not?
- Solar panel insurance covers installation errors by solar installers, electrical malfunctions, third-party injuries from panel failure, fire risk specific to solar technology, and damages caused by system detachment or grid disturbances related to net metering, which may not be included in standard homeowners insurance.
- Can I include solar liability insurance coverage if I join a community solar investment like Solar Plus Garden?
- Yes, the Solar Plus Garden model provides insurance solutions customized to separate legal entities managing the solar plant and the community garden. This structure allows coverage designed to reflect the specific liability risks of investors and community members independently.
Conclusie
Homeowners with solar power systems should proactively obtain solar liability insurance to bridge coverage gaps left by traditional homeowners insurance and shield themselves from liabilities associated with solar panels. Coverage requirements depend on the type of solar panel—particularly tier 2 solar systems—installation certification, and applicable regulatory standards. Participants in investment platforms such as Solar Plus Garden must understand how insurance coverage integrates into the project’s legal and financial structure, with policy updates necessary following system modifications or regulatory changes to maintain appropriate protection and compliance.
Gerelateerde artikelen
- Comprehensive Guide to Solar Smart Meters: Understanding, Installation, and Monitoring for Homeowners
- Investeringsmogelijkheden in zonneparken in 2026: een uitgebreide gids voor investeren in zonne-energie
- Investeer vandaag nog in zonne-energie: uw complete gids voor duurzame investeringen in hernieuwbare energie.