How to Secure Your Solar Investment: Comprehensive Insurance and Protection Strategies
Understanding the Role of Insurance in Protecting Solar Energy Investments
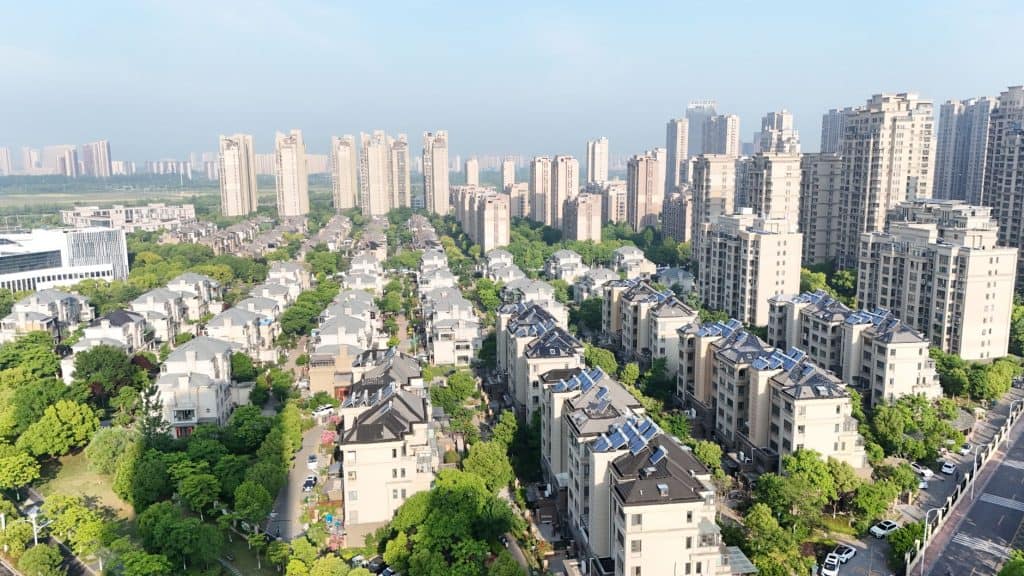
Solar investment insurance and protection comprise specialized insurance policies explicitly designed to cover solar energy assets such as fotonaponska (PV) solar panels, inverters, mounting systems, and other components of a solar system. These policies address risks that standard home insurance typically excludes, such as solar panel operational failures, microinverter breakdowns, and renewable energy system-specific liabilities.
Standard home insurance ili homeowners insurance policies generally focus on covering structural elements of a home from risks like fire or theft but may exclude or limit coverage for solarni paneli, especially in cases of operational defects or damage caused by environmental factors unique to solar installations, including hail or wind speeds exceeding 25 meters per second. Therefore, a tailored solar panel insurance product is necessary to ensure these assets are adequately covered.
For investors engaging with Solar Plus Garden’s 10 MW solar project, insurance coverage forms a key component of risk management within the project’s financial structure. Through the integrated članstvo u zajednici model, membership fees contribute not only to the operational expenses of the solar plant but also directly fund insurance premiums and related risk mitigation measures. This structure ensures that investor capital is shielded against both physical and financial disruptions affecting solar asset performance.
Understanding the distinction between solar energy insurance and general home insurance enables investors to better assess the durability of their investicija u solarnu energiju and accurately factor coverage into long-term return forecasts, consistent with current industry risk assessments.
Types of Insurance Policies Relevant for Solar Panels and Solar Systems
Owners and investors who install solar panels should consider various insurance policies to ensure comprehensive protection:
- Property insurance: Covers physical loss or damage to solar panels, inverters, racking systems, and related equipment resulting from insured perils such as storms (hail, wind over 25 m/s), fire, vandalism, and theft. Policies often specify limits per incident and require documented loss assessments within two weeks of damage discovery.
- Liability insurance: Provides coverage against third-party injury or property damage claims arising from the solar installation, particularly relevant when solar equipment is accessible or installed in community or commercial settings. This insurance protects the solar installer, project operators, and sometimes individual investors depending on contractual obligations.
- Equipment breakdown coverage: Offers financial compensation for mechanical or electrical failures of key components such as inverters, DC/AC converters, and wiring, excluding typical wear and tear. Coverage usually involves a deductible and compensation based on repair or replacement costs within specified warranty-like timeframes, often aligned with manufacturer guarantees.
- Contractor’s and professional liability insurance: Applies mostly to solar installers and system developers, covering claims of faulty installation or design errors that cause functional impairment or damage. This policy is essential during the construction and commissioning phases and complements property and operational coverage.
Solar projects typically require different insurance arrangements during installation versus operational phases. Installation risks are often covered by contractors’ insurance with project-specific endorsements, while post-commissioning operational risks require dedicated solar insurance policies. Insurers explicitly distinguish these phases in policy wordings and exclusions, with operational coverage activating only after handover and system commissioning.
Common Risks to Solar Investments and How Insurance Mitigates Them
Insurance policies tailored for solar systems consider the following primary risk categories:
- Physical risks: Weather events such as hailstorms (hailstones >20 mm diameter), high winds (over 25 m/s), lightning strikes causing electrical surges, fire initiated by electrical faults, theft, and damage from animals like birds or rodents can physically impair solar panels. Documented cases show that insurance claim repairs range from 14 to 56 days, depending on damage scale and local contractor availability.
- Operativni rizici: Failures of critical components such as string inverters, microinverters, or photovoltaic modules reduce system output and cause revenue loss. Comprehensive solar insurance policies include provisions for equipment breakdown, covering costs to restore output and mitigate prolonged downtime.
- Legal and regulatory risks: Non-compliance with permits, zoning laws, or national technical standards (e.g., IEC 62446 series for PV system inspection and documentation) can trigger penalties or forced shutdowns. Some liability or professional indemnity policies reimburse related legal expenses or fines up to policy limits, helping investors manage compliance risk.
- Finansijski rizici: Revenue interruption due to equipment failure or insured physical damage is addressed by business interruption or loss-of-income coverage, which compensates for earnings lost during repair periods, often capped to 6-12 months of projected revenue based on feed-in tariffs or power purchase agreements.
Solar insurance policies establish strict claim protocols, including evidence submission timelines (commonly within 7 days), professional damage assessments, and repair action plans. Insurers partnering with solar projects typically maintain experience handling claims within regional frameworks such as Estonian and Serbian market environments, improving claim efficiency and investor confidence.
Integrating Solar Panel Coverage into Homeowners Insurance Policies
Property owners installing solar panels should evaluate existing homeowners insurance to verify if solar panels are covered as part of the dwelling or require additional endorsements. Key evaluation points are:
- Inclusion criteria: Verify if solar panels are integrated into dwelling coverage or listed as separate assets, which may necessitate policy riders or endorsements that specify coverage limits typically aligned with panel replacement costs.
- Policy adjustments: Notify insurers promptly upon solar installation to enable updating the home insurance policy with appropriate riders or endorsements. Supporting documentation includes manufacturer specifications, installation certificates, and warranties, often required for underwriting.
- Exclusions and limitations: Common exclusions may consist of wear and tear, degradation from environmental soiling, or damage during maintenance activities, all necessitating supplementary solar panel insurance for comprehensive protection.
- Standalone solar insurance versus policy riders: While riders add limited coverage within a homeowners policy, standalone solar insurance policies typically offer broader guarantees, including coverage for operational failure and professional liability, which is especially critical for larger-scale solar systems such as Solar Plus Garden’s utility-scale 10 MW installation.
- Community membership considerations: Within the Solar Plus Garden structure, obtaining a Garden membership confers access to community benefits but does not substitute for individual or corporate insurance policies. Members must ensure independent coverage aligns with project requirements and personal risk tolerance.
Commonly required home insurance policy endorsements include stipulations that reflect the increased asset value brought by solar panels, with potential premium adjustments ranging from 5% to 15% based on regional risk profiles and building characteristics.
The Process and Best Practices for Insuring Your Solar Investment
To insure your solar correctly, the following sequential steps are advised:
- Risk assessment before installation: Evaluate the local climate risk (hail frequency, wind speed zones per regional meteorological data), asset value, and financing conditions that drive insurance needs.
- Detailed system documentation: Maintain an inventory of all solar system components, including PV panel make/model, inverter type, installation date, certifications from recognized bodies (e.g., TÜV Rheinland, UL), and commissioning reports.
- Engagement with specialized insurers: Collaborate with insurance providers experienced in solar energy insurance to design policies covering property damage, operational interruptions, and liability with explicit coverage limits and deductibles suitable for the investment scale.
- Annual policy review: Update insurance agreements to reflect system expansions, technology upgrades (such as adding energy storage), and evolving regulatory requirements, avoiding coverage gaps or underinsurance.
- Third-party verification and transparent payment: Utilize independent technical audits and leverage escrow-controlled premium payments as Solar Plus Garden implements to ensure proper allocation and reduce financial risk.
Underwriting times vary but are typically between 5 and 21 business days for residential and small commercial systems; utility-scale projects may require longer due to complexity. Claims processing after an accepted event generally completes within 30 to 60 days, depending on inspection, parts availability, and repair scheduling.
How Solar Plus Garden’s Community Membership Model Supports Sustainable Risk Management
The Solar Plus Garden framework incorporates a community membership approach that enhances sustainable risk sharing and investor protection through:
- Membership fees structure: A one-time €200 Garden membership fee provides access to community governance and supports solar project insurance alongside operational expenditures. Optional Garden Box subscriptions (€20/month) fund local agrivoltaic activities with traceable finance flows.
- Legal separation: The Garden community functions under a distinct legal entity from the Serbian DOO that owns the solar assets, assuring functional and financial transparency, and clearly delineating community membership rights from solar asset ownership.
- Escrow and financial controls: Membership contributions are managed through escrow accounts compliant with Estonian and Serbian fiduciary laws, delivering financial integrity and preventing fund diversion.
- Membership capacity and risk pooling: Limited to 3,000 Garden parcels to maintain effective risk sharing and operational manageability. This cap supports a diversified pool over which insurance costs and community risks are distributed, lowering individual financial exposure.
- Scalable risk management: The model enables collective negotiation of insurance terms, potentially reducing per-member premiums and fostering resilience against localized claim surges or operational challenges.
This structure balances operational efficiency with investor protection and community benefits, providing a tested framework for integrating solar energy insurance within a cooperative financial and legal ecosystem.
Evaluating Cost Implications of Solar Investment Insurance for Small and Medium Investors
Insurance premiums associated with solar investments depend primarily on the system scale, site-specific risk factors, and insurance coverage scope. Key cost considerations entail:
- Premium ranges: For residential to small commercial installations (up to 100 kW), insurers typically charge annual premiums of 0.5% to 2% of total system capital value. Premium calculation factors include geographic risk indexes such as hail frequency and wildfire risk zones.
- Bundled versus standalone policies: Combining solar insurance with standard homeowners insurance can reduce upfront premium costs but may exclude coverage for operational failures or specialized solar system liabilities.
- Return on investment impact: Insurance costs are integral to the operational expenditure profile and must be incorporated into financial models. Correctly insured assets maintain steady revenue streams by reducing unexpected repair costs and downtime.
- Budget planning: Investors should integrate both the Solar Plus Garden membership fees and dedicated insurance premiums into comprehensive project budgets to maintain financial discipline and risk coverage.
- Financing advantages: Demonstrated coverage with seasoned insurers enhances lender confidence, often improving financing terms such as interest rates or loan-to-value ratios.
Applying premium calculations as a percentage of system value assists small and medium investors in planning for insurance costs within Solar Plus Garden’s scalable investment framework.
Legal and Regulatory Standards Governing Solar Investment Insurance in Estonia and Serbia
Solar investment insurance for Solar Plus Garden’s cross-border entities complies with regulatory requirements applicable in both Estonia and Serbia, including:
- National insurance laws: Obligations under Estonian and Serbian insurance codes mandate insurer licensing, policyholder disclosures, and claims handling standards aligned with European Union directives and local regulations.
- Escrow fund regulations: Financial governance concerning escrow accounts follows regional fiduciary standards, ensuring controlled use of membership fees and transparent financial reporting.
- Installation compliance: Solar PV installations must meet national building codes and electrical standards—such as IEC 61730 for module safety and IEC 62109 for inverter safety—which factor into insurance underwriting risk assessments.
- Regulatory reporting: Investors and project operators adhere to disclosure requirements for insurance status, claim histories, and operational impacts under project agreements and local securities laws.
- Alignment with investor-ready structures: Solar Plus Garden’s Estonian OÜ and Serbian DOO dual legal framework exemplify compliance with contemporary best practices for transparent governance and risk management as of 2026.
Compliance with these standards enables predictable insurance coverage and reinforces investor protection in multinational renewable energy investments.
Često postavljana pitanja
Does my homeowner’s insurance automatically cover the solar panels I install?
Coverage for solar panels under homeowners insurance varies by insurer and policy. Most standard policies require explicit endorsements or riders to cover solar panels. Verification of coverage limits, applicable exclusions, and whether additional or specialized solar panel insurance is needed is essential to ensure full protection of your solar assets.
What specific risks do solar investment insurance policies cover that homeowners insurance does not?
Solar investment insurance policies cover unique risks including mechanical and electrical equipment breakdowns, operational downtime compensation, professional liability of solar installers, and damage scenarios specific to solar technology such as soiling or panel microcracks, which are commonly excluded from general home insurance policies.
How does Solar Plus Garden integrate insurance and community membership fees to protect investors?
Solar Plus Garden utilizes a transparent financial mechanism where the Članstvo u bašti fee finances not only the solar project but also insurance premiums and operational expenses. The legal separation of community membership from solar asset ownership and the use of escrow accounts ensure that investor funds are safeguarded and allocated strictly according to project governance, reinforcing accountability and risk mitigation.
What steps should I take to insure my solar panels when joining a community solar project like Solar Plus Garden?
Begin by documenting your solarni panel make, model, inverter types, and installation credentials. Review solar energy insurance options recommended by the community or insurer partners. Liaise with insurance providers to tailor coverage for your investment size, including property, operational, and liability protections. Maintain active engagement with community updates on insurance policy administration to ensure ongoing compliance and coverage adequacy.
Zaključak
Effectively protecting your solar investment requires selecting insurance policies tailored explicitly for solarna energija assets, understanding how these policies complement or extend beyond your existing homeowners insurance, and leveraging community-backed models like Solar Plus Garden’s membership system for transparent funding and risk distribution. Annual policy reviews, compliance with evolving legal frameworks, and aligning insurance structures with operational realities are essential to maintaining comprehensive solar panel protection. Remaining informed about regulatory, technological, and market developments ensures your solar investment delivers sustained financial and environmental benefits.