

Navigating Solar Investment Mezzanine Financing: A Detailed Guide for Project Developers and Investors
Understanding the Role of Mezzanine Financing in Solar Project Capital Stacks
Mezzanine finance definition identifies it as a specialized form of subordinated debt within the capital stack of zonne-energieprojecten, positioned between senior debt en de equity component. It addresses the funding gap encountered when initial financing requirements exceed limits placed by secured loans and available equity contributions. In a standard 10 MW solar asset financing structure typical to projects like Solar Plus Garden, the capital stack breaks down to approximately:
- Senior Debt: Typically comprises 50-70% of total capital, secured against project assets such as solar panels, inverters, and land lease rights, carrying lowest risk due to priority in cash flow claims.
- Subordinated Debt (Mezzanine Finance): Constitutes about 10-25% of capital, with junior priority behind senior lenders, assuming higher risk in exchange for increased interest rates and possible equity participation.
- Equity Component: Usually accounts for 10-30% of project capital, representing ownership stakes held by project developers and investors who absorb residual risk but benefit from upside in operational success.
Mezzanine lenders fill the funding void restricted by senior lenders’ collateral and coverage ratios, often capped by loan-to-value (LTV) thresholds at 70-75% under project finance debt standards. In addition to debt service, mezzanine arrangements commonly include warrants of convertible notes to provide capital providers flexibility in capturing project uplift while maintaining debt status initially.
This capital structure segmentation enables distinct investor profiles: senior lenders prioritize collateral-backed stability, mezzanine lenders accept moderate credit risk with enhanced investment returns, and equity investors retain maximum upside aligned with project success or failure.
Key Structural Components of Mezzanine Financing for Solar Investments
Solar mezzanine financing typically includes a blend of financial instruments and defined terms that differentiate it from senior loans and pure equity:
- Interest Rates: Reflective of elevated investment risk due to subordinated position, rates often range between 8% and 15% per annum. Rates are set after assessing project credit risk, borrower profile, and sector benchmarks within the renewable energy sector.
- Warrants: Allocated to mezzanine lenders as an incentive, these usually represent 5% to 20% of project equity at issuance. Warrants offer the right to purchase equity at predetermined terms, linking debt returns to project exit valuations or refinancing events.
- Convertible Notes: Convertible debt instruments that allow lenders to convert debt into equity when specific triggers occur, such as failure to meet debt service obligations or at maturity, facilitating equity participation without initial dilution to developers.
Mezzanine debt can be structured as either secured loans of unsecured loans. Secured mezzanine debts are backed by secondary collateral such as future cash flows from power purchase agreements (PPA) or specific project equipment, aligning with credit enhancement practices to reduce lender risk. Unsecured mezzanine loans depend heavily on contractual loan covenants and the project’s operational viability, allowing more flexible but riskier conditions.
Loan covenants in mezzanine financing agreements impose operational limitations that may restrict additional indebtedness, mandate reserve account funding, or require maintenance of debt-service coverage ratios (DSCR) often targeted at 1.2x or higher for subordinated lenders. Defaults trigger enforcement measures stricter than those in senior debt agreements due to heightened risk exposure.
Cash Flow and Investment Duration Considerations in Mezzanine Financing
Thorough cash flow analysis serves as the foundation for determining mezzanine financing feasibility and repayment structuring. Projected revenue streams from the sale of electricity under long-term PPAs, banking on stable solar irradiance data and operational costs, define the ability to service both senior debt and mezzanine obligations.
The common investment duration, or investment horizon, for mezzanine finance aligns with the stable operational phase of typical solar projects, spanning 5 to 8 years. This timeframe corresponds to the initial asset depreciation period under International Financial Reporting Standards (IFRS) and common PPA terms in Central and Eastern Europe, including Serbia and Estonia.
Financial modeling encapsulates these assumptions to produce payment schedules involving periodic interest payments—often semi-annual or quarterly—and principal amortization aligned with the project’s net cash inflows after senior debt service and operating expenses.
- The balance of principal amortization and interest-only periods is calibrated to maintain a DSCR that satisfies mezzanine lenders while mitigating default risk.
- Over-aggressive repayment schedules relative to seasonal solar output variability can create refinancing needs or trigger covenant breaches.
Forecasts incorporate variable tariff indexing mechanisms, expected degradation rates of fotovoltaïsch modules (~0.5% per year), and scheduled maintenance costs compliant with industry norms such as IEC 62446 for PV system performance verification.
Balancing Equity Participation and Risk in Solar Mezzanine Financing
Mezzanine finance’s hybrid return structure blends fixed investment returns with potential equity upside. Warrants En convertible notes are common tools that enable subordinated debt holders to convert their position to equity, typically exercised upon reaching predefined financial or operational milestones.
This introduces measurable equity dilution risk to existing project developers’ equity stakes. Typical warrant coverages linked to mezzanine financing cause 5% to 15% dilution, contingent on negotiation specifics, conversion terms, and project valuation at exercise.
Unlike direct equity investors, mezzanine financiers initially lack voting rights and control, preserving governance structures until conversion occurs. This staged risk profile informs investment strategies by allowing mezzanine lenders to limit downside exposure while sharing in project growth under stipulated conditions.
Credit enhancement features integral to mezzanine finance reduce investment risk by mechanisms such as cash sweep provisions that prioritize debt repayment with available cash after operational expenses or creation of reserve accounts to cushion against cash flow volatility. These enhancements address subordinated position vulnerabilities not mitigated by senior debt security packages.
Due Diligence and Legal Frameworks for Solar Mezzanine Financing Deals
Prior to committing capital, rigorous due diligence is undertaken across key dimensions to confirm project viability and assess investment risk. Due diligence protocols typically encompass:
- Technische beoordeling: Verification of solar panel technology compliance with IEC 61215 and IEC 61730 standards, inverter certifications, and site resource analysis.
- Contractual review: Examination of PPAs for duration (often 15-20 years), tariff structures, counterparty creditworthiness, and termination provisions.
- Financial projections check: Validation of financial modeling assumptions against historical irradiance data and market benchmarks to stress test cash flow sustainability under variable scenarios.
- Legal and regulatory compliance: Assessment of permits, ownership structures, and jurisdictional requirements, particularly scrutinizing cross-border frameworks relevant to Estonian OÜ and Serbian DOO entities in models like Solar Plus Garden.
- Loan covenants and financing agreements review: Detailed analysis of rights, enforcement mechanisms, and restrictions to ensure balanced protections for mezzanine lenders.
Implementing a transparent payment and escrow model governed by automated controls ensures proceeds flow in accordance with financing agreements, minimizing risk of misuse. This process is fundamental to investor-ready operations and compliance with capital markets standards for regulated investments.
Impact of Mezzanine Financing on Solar Project Return on Investment and Community Models
Incorporation of mezzanine financing increases the weighted average cost of capital (WACC) compared to debt-only structures by elevating interest obligations beyond senior debt levels, but generally remains below pure equity financing costs. This enhances capital availability while maintaining an acceptable return on investment.
Within the Solar Plus Garden’s 10 MW solar plant configuration, mezzanine financing facilitates:
- Augmented funding capacity beyond traditional secured loans limits, enabling higher project scale and scope.
- Stable operational cash inflows derived from PPAs to service layered debt tranches and fund community activities sustainably.
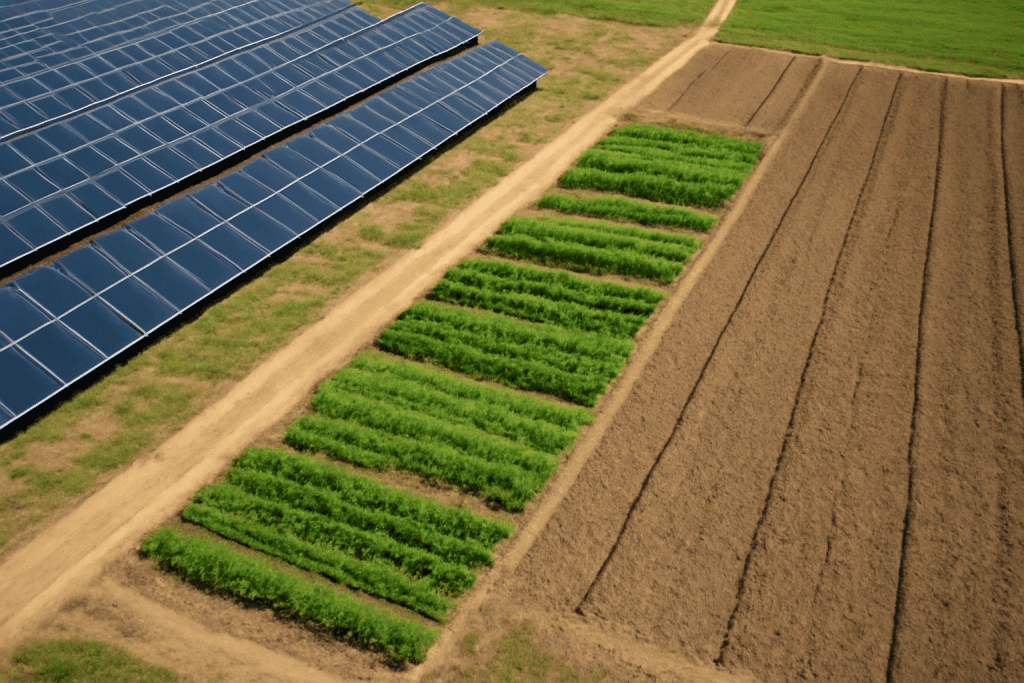
- Access for small and medium investors through a regulated platform that combines solar asset finance with a community and agrivoltaic model.
De lidmaatschap van de gemeenschap framework, supported by membership fees reinvested into solar asset maintenance and agrivoltaic operations, exemplifies integrated capital and stakeholder management designed for long-term resilience. This aligns risks and returns with social value generation, extending common project finance models.
Investor Perspective: Evaluating Mezzanine Financing Opportunities in Solar
Investors must approach mezzanine financing with an evaluation framework balancing risk and reward within the renewable energy sector context. Key considerations include:
- Targeted risk-adjusted returns commonly range from 10% to 15% IRR, reflecting elevated risk over senior loans but reduced volatility compared to pure equity.
- Assessment of capital security through collateral quality, secondary lien positions, and robustness of covenants governing debt service priority and default remedies.
- Comparison with alternative capital structures, considering how mezzanine finance complements portfolio diversification and exposure to operational solar project cash flows.
Due diligence on financing terms, including scrutiny of covenant thresholds, enforcement rights, and conversion conditions, is critical. Investors also monitor macroeconomic factors such as interest rate trends, regulatory incentives, and solar market dynamics which influence overall project investment returns.
Veelgestelde vragen
- What distinguishes mezzanine financing from traditional senior debt in solar projects?
- Mezzanine financing falls between senior debt and equity in the capital stack, exhibiting higher investment risk with elevated interest rates and equity participation rights like warrants of convertible notes. Senior debt is fully secured with priority repayment claims, while mezzanine lenders accept subordinate claims for increased return potential.
- How does mezzanine financing affect the ownership structure of a solar project?
- Mezzanine financing can lead to equity dilution of original owners when instruments such as warrants of convertible notes convert into equity under specified conditions, typically diluting existing equity holders by 5% to 15% depending on the terms negotiated.
- What are typical durations and returns expected from mezzanine investments in solar energy projects?
- Investment duration generally ranges from 5 to 8 years, reflecting the solar project’s operational life phase targeted by mezzanine structures. Expected returns vary from approximately 8% to 15% annually, scaled to project-specific risks and agreed financing terms.
- What due diligence should investors perform before entering a solar mezzanine financing agreement?
- Investors should validate project viability, audit cash flow analysis models, confirm full legal compliance including permits and corporate governance, and thoroughly examine loan covenants within financing agreements to ensure enforceability and protection against investment risk.
Conclusie
Project developers and investors considering solar investment mezzanine financing must build investment decisions upon precise financial modeling and comprehensive legal due diligence. The composition of the capital structure—balancing senior debt, subordinated debt, En equity components—should reflect the risk tolerance and operational realities of 10 MW solar projects.
Firm adherence to transparent financing agreements, robust enforcement of loan covenants, and implementation of clear cross-jurisdictional governance frameworks, exemplified by models such as Solar Plus Garden’s Estonian OÜ and Serbian DOO entities, underpin sound financing decisions.
Ongoing monitoring of market interest rates, regulatory shifts, and operational performance metrics remains necessary to adapt financing structures. Executed with discipline, mezzanine financing bridges the funding gap efficiently within capital markets, enabling scalable solar asset financing combined with community integration and sustainable impact.